
Commercial Real Estate Financing Options: Bridge Loans, Hard Money, and Private Capital Explained
September 18, 2026
Stop obsessing over a decimal point while your competition closes on the distressed property you spent weeks scouting. Right now, a “high” rate isn’t your enemy. Stagnation is. You’re tired of losing deals to cash buyers while waiting for a bank’s red tape. No more waiting. No more generic term sheets packed with hidden fees. You know that Phoenix hard money interest rates 2026 are volatile. The old rules of thumb just don’t apply anymore. You need capital that moves as fast as the Valley market does.
We’re here to give you a reality check. This guide will strip away the confusion and show you how to master the 2026 lending landscape. You’ll learn why savvy investors prioritize speed and leverage over the base interest rate to maximize their actual profit. We’re breaking down the total cost of capital for a Phoenix flip. We’ll show you how to secure fast, asset-based capital that puts you ahead of the pack. It’s time to stop fearing the rate and start winning the deal. Results matter more than formalities.
Key Takeaways
- Navigate the shifting volatility of Phoenix hard money interest rates 2026 to keep your investment strategy ahead of the curve.
- Realize why chasing rock-bottom bank rates is a losing strategy when speed is the only way to beat cash buyers to distressed inventory.
- Identify how high-accuracy ARV reports and property-focused metrics act as your primary leverage for securing better loan terms.
- Shift your focus from base interest rates to the total cost of capital to protect your profit margins on every Phoenix flip.
- Build a professional “Deal Package” that proves your property’s value and forces lenders to move at the speed of your business.
The 2026 Phoenix Hard Money Landscape: Trends and Projections
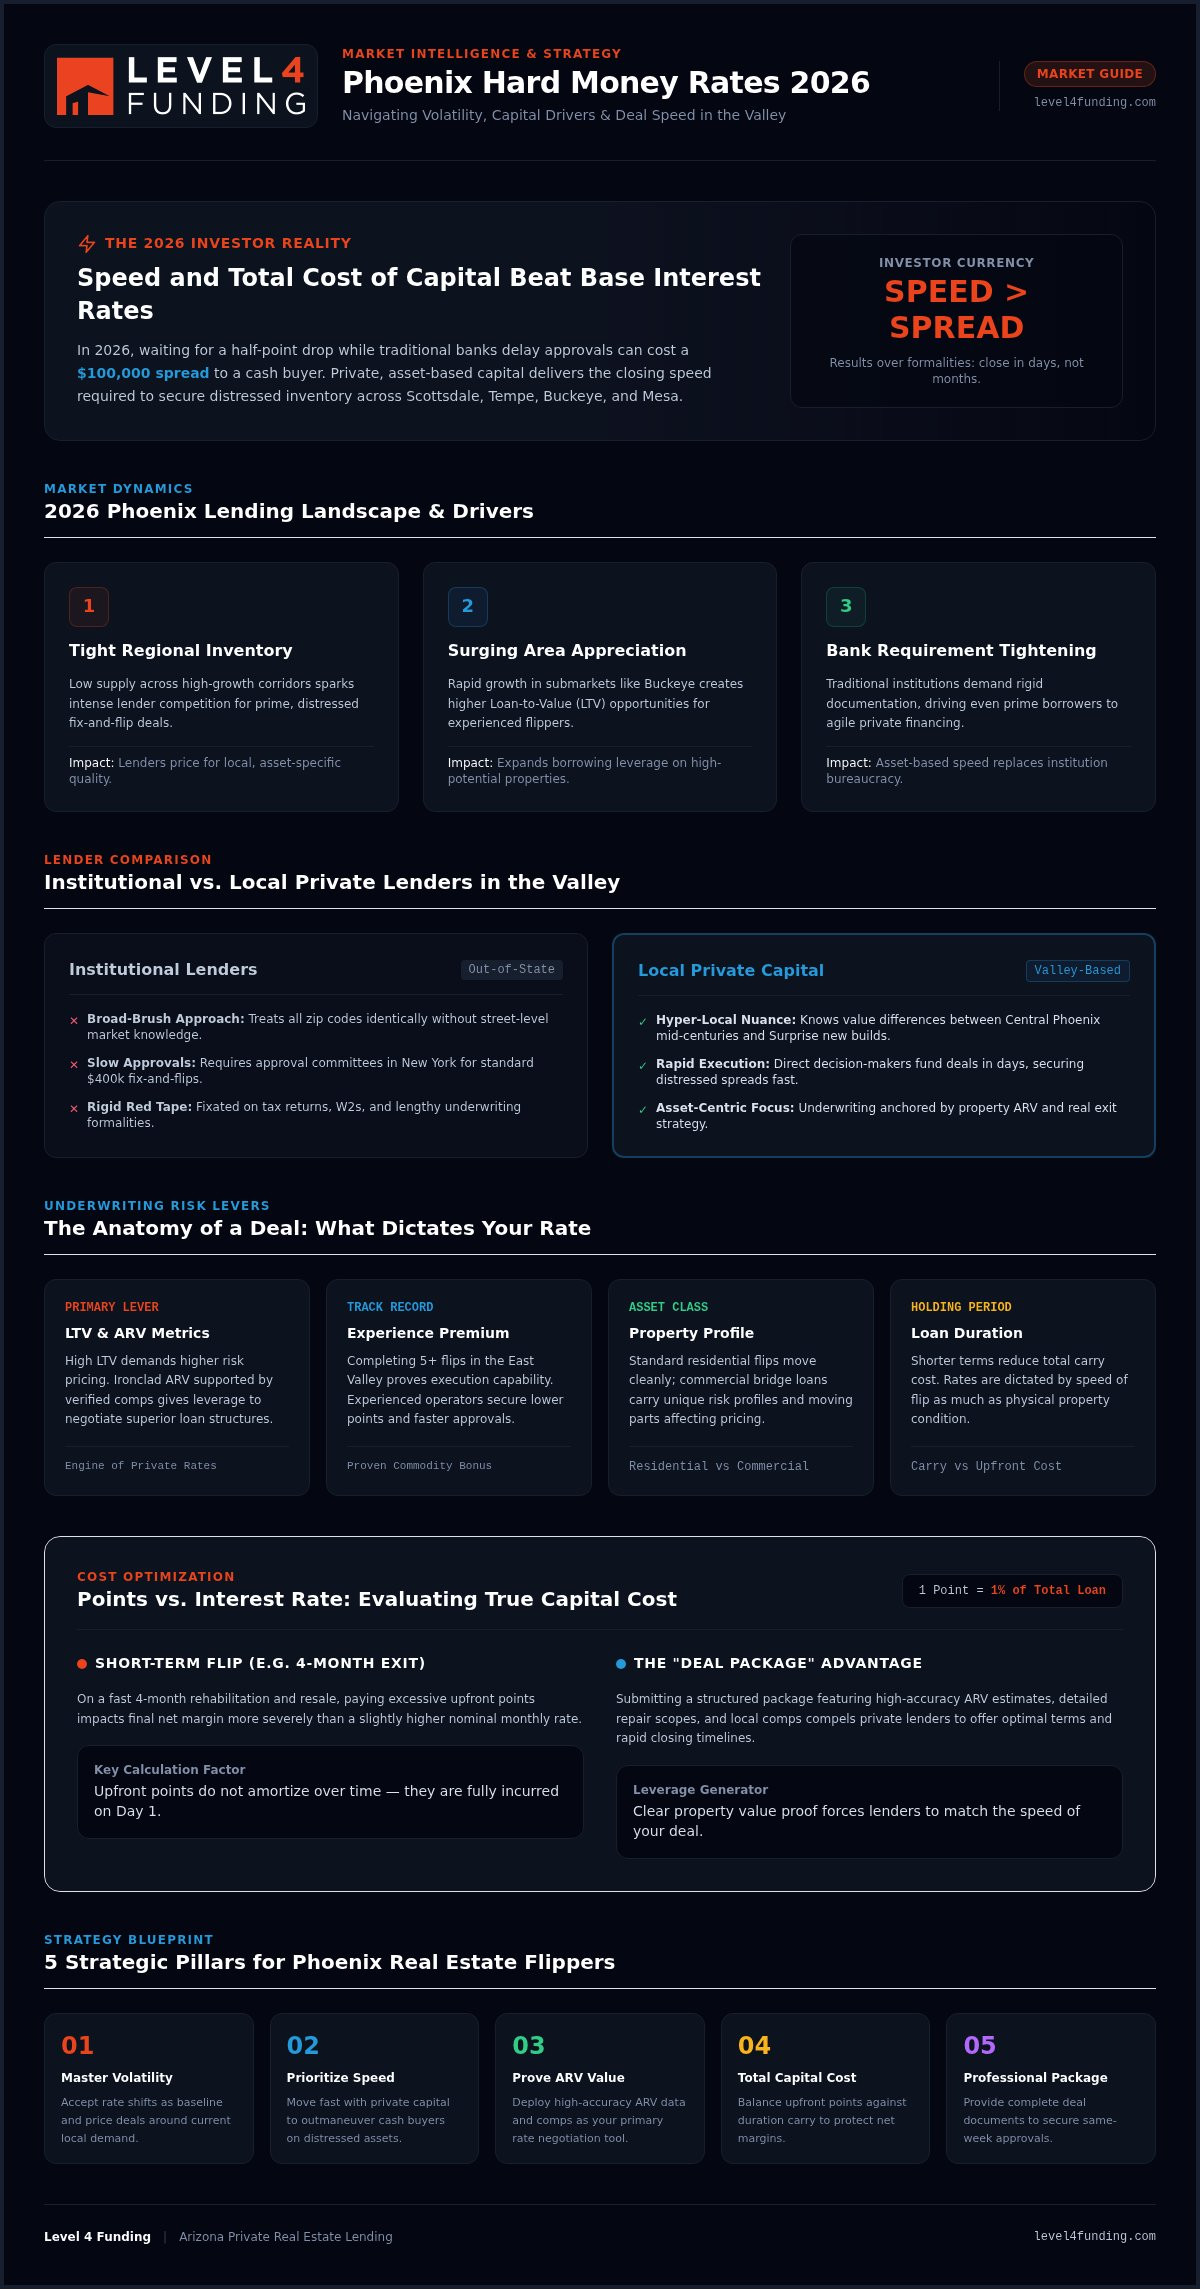
Phoenix isn’t for the faint of heart in 2026. Volatility is the new baseline. You see it in Scottsdale. You feel it in Tempe. Traditional banks have retreated into their shells, clutching their rigid requirements. They want perfect credit and years of tax returns. You don’t have time for that. You have a flip that needs funding yesterday. This is why hard money loans have become the lifeblood of the Valley. Private capital fills the gap that institutions left behind. It’s about the asset, not the red tape. Local investors are ditching the big-box banks. They’re choosing partners who speak their language and move at their pace.
Market Drivers for Arizona Rates
Inventory is tight. Demand in Buckeye and Mesa is surging. These aren’t national trends; they are local realities. When inventory drops, lender risk appetite shifts. Phoenix hard money interest rates 2026 reflect this tension. Institutional lenders often apply a broad brush, but local private lenders understand the street-level value. They know a “good” deal in Mesa isn’t the same as one in Scottsdale. They price for the specific opportunity, not a generic zip code. Several factors are currently driving the Arizona market:
- Low inventory in high-growth corridors increases lender competition for quality deals.
- Rapid appreciation in areas like Buckeye creates higher LTV opportunities for savvy flippers.
- Traditional bank tightening forces even “prime” borrowers into the private sector for speed.
The role of institutional vs. local private lenders in the Valley is shifting. Institutions bring volume, but they lack the local nuance. They don’t know the difference between a mid-century modern in Central Phoenix and a new build in Surprise. Local lenders do. They live here. They move faster because they don’t have to call a committee in New York to approve a $400,000 fix and flip.
The 2026 Investor Outlook
Stop waiting for rates to drop. That’s a rookie mistake. While you wait for a half-point decrease, a cash buyer just snatched your $100,000 spread. In 2026, rate stability is a myth. The only thing that matters is the speed of your execution. Understanding Phoenix hard money interest rates 2026 is about understanding local risk and the cost of missed opportunities. The Phoenix market rewards the fast. It punishes the hesitant. Your advantage isn’t a lower spread. It’s the ability to close in days. Leverage is your tool. Speed is your currency. If the numbers work at current levels, pull the trigger. You aren’t just buying property. You’re buying time. You’re buying the right to profit before the next guy even gets his appraisal back. Results over formalities. Every single time.
What Drives Phoenix Hard Money Interest Rates: The Anatomy of a Deal
Stop guessing why your term sheet looks the way it does. Lenders don’t pull numbers out of thin air. They calculate risk using specific levers. The two biggest? Loan-to-Value (LTV) and After-Repair Value (ARV). These metrics are the engine room for Phoenix hard money interest rates 2026. If you’re pushing for a high LTV, you’re asking the lender to take more of the hit if things go south. They’ll charge you for that privilege. Conversely, a rock-solid ARV backed by ironclad comps gives you the leverage to negotiate better terms. Asset-based lenders care about the property’s heartbeat, not just your FICO score. They want to see a deal that stands on its own two feet.
Your track record is the “Experience Premium.” It’s the difference between a smooth approval and a mountain of questions. If you’ve successfully exited five flips in the East Valley, you’re a proven commodity. Lenders reward that history with lower points and better structures. If you’re a rookie, expect to pay a bit more while you prove you can handle the pressure. Property type also moves the needle. A standard residential flip is straightforward; a commercial bridge loan involves more moving parts and different risk profiles. Even the duration of the loan matters. Shorter terms might have higher points but lower total interest carry. In the current market, Phoenix hard money interest rates 2026 are dictated by the speed of the flip as much as the property’s condition.
Points vs. Interest: Understanding Total Cost
Don’t get blinded by a low monthly rate. Points are the upfront entry fee, and they can be the silent killer of your margins. In the Phoenix market, one point is one percent of the loan. If you’re planning a quick 4-month exit, high points can be more expensive than a higher interest rate. While Federal Reserve interest rate data influences the broader financial climate, private capital follows its own internal logic. You need to calculate the total cost of capital from day one to the day you sell. It’s the only way to know if your spread is actually safe. You aren’t just paying for money; you’re paying for the opportunity to profit.
Risk Assessment in the Valley
Location is everything. A project in Glendale has a different risk profile than a luxury renovation in Sedona. Lenders look at the scope of work too. A “rehab heavy” project with structural changes is a different beast than a “cosmetic” paint-and-carpet job. The more complex the project, the more “insurance” the lender needs via the rate. If you want a partner who looks at the deal’s potential instead of just your paperwork, look into hard money loans that focus on asset value. We value the property’s future as much as you do. Decisions are fast. The process is direct. That’s how you win in 2026.
The Interest Rate Myth: Why Winners Don’t Wait for Bank Rates
Stop chasing the lowest rate. It’s a trap. While you’re filling out bank forms, the property is gone. A 4% difference in interest is a rounding error on a successful flip. It’s irrelevant if you lose the deal entirely. In the 2026 market, speed is your only real currency. Winners don’t wait for bank approvals. They secure the asset. They move on. If you’re obsessing over a decimal point while a cash buyer snatches your $100,000 spread, you’ve already lost. Results matter more than formalities. You need capital that keeps up with your ambition.
The Opportunity Cost of Cheap Money
Calculating the lost profit from a 45-day bank delay is a wake-up call. That’s 45 days of holding costs. 45 days of lost momentum. For a local investor, that “cheap” loan could easily cost $50,000 in missed profit. High-energy investors don’t see interest as a hurdle. They see it as a line-item expense. It’s like lumber or paint. It’s the price of admission for a six-figure payday. Banks want your life story and three years of tax returns. We want your deal. Don’t let bureaucratic friction kill your ROI. Phoenix hard money interest rates 2026 are a tool for execution, not a barrier to entry.
Banks operate on a “no” until proven otherwise. We operate on the deal’s merit. No red tape. No endless committees. Just results. If you’re waiting for a traditional lender, you’re not an investor; you’re a spectator. The real players are already on the ground in Phoenix, closing deals in 7 to 10 days. That’s the shortcut. That’s the reality of 2026. You either have the capital to strike, or you’re watching someone else cash the check.
Leveraging Hard Money for Growth
Agility wins in 2026. You need fix and flip loans that move at your pace. Why do one deal with your own cash when you can do three with ours? Recycling capital is the secret to high-volume flipping in Arizona. Wealthy investors use other people’s money regardless of the current environment. They don’t care about the base rate. They care about the spread. If the deal makes sense at one level, it makes sense slightly higher. The goal is volume. The goal is scaling. Phoenix hard money interest rates 2026 are just one variable in a much larger profit equation. They aren’t the whole story. Move fast. Scale hard. Leave the bank paperwork to the amateurs. Your success depends on your ability to deploy capital today, not next month.
How to Secure the Best Hard Money Rates in Phoenix
Stop acting like an amateur if you want professional terms. Lenders smell uncertainty from a mile away. They price that fear into your points. To win the battle for Phoenix hard money interest rates 2026, you need a “Deal Package” that leaves zero room for doubt. This isn’t a suggestion. It’s your leverage. A high-accuracy After-Repair Value (ARV) report is the backbone of this strategy. Forget generic online estimates. Use real, street-level comps. When you prove you understand the Phoenix market better than the lender’s algorithm, you’ve already won half the negotiation. Local expertise reduces lender anxiety. Lower anxiety means lower rates.
Optimizing Your Loan-to-Cost (LTC)
How much skin do you have in the game? It’s a simple question with big consequences. A higher down payment usually triggers the most competitive terms. However, you have options. Cross-collateralization allows you to use equity in other properties to secure your new deal. This move drastically reduces lender exposure. It often leads to a significant drop in your interest costs. You might think hard money loan requirements are rigid barriers. They aren’t. They are starting points for negotiation. If the property talks loud enough, the requirements get a lot quieter. Results over rules. Every deal has a price.
Deal Presentation Secrets
Don’t just send an address and a prayer. Send a blueprint for profit. A line-item rehab budget proves you’ve done the work. It shows you won’t be calling for more cash when the foundation reveals a surprise. Use professional photos. Provide a clear exit strategy. This is how you earn the “Experienced Investor” discount. Even if you’re early in your career, a professional presentation builds immediate authority. Lenders move faster when they don’t have to chase you for paperwork. Speed lowers their operational cost. They pass those savings to you in the form of better Phoenix hard money interest rates 2026. Stop waiting for the market to change. Change your approach. Get your deal funded now and stop leaving your profit to chance.
Level 4 Funding: Your High-Speed Ally in the Phoenix Market
Traditional lenders are stuck in the past. They want your tax returns. They want your life story. We want your deal. At Level 4 Funding, we don’t play the waiting game. We provide assertive, no-nonsense capital for serious Arizona investors who understand that timing is everything. Our focus is asset-based. This means the property talks louder than the paperwork. If the value is there, the funding is there. We’ve seen every obstacle in the Valley and we know how to navigate around them. You aren’t just getting a loan; you’re getting a street-smart ally who values results over formalities. Why settle for a “maybe” from a bank when you can get a “yes” from a partner in days?
Our local expertise isn’t just a tagline. We live and breathe the Phoenix, Scottsdale, and Tucson markets. We know which neighborhoods are heating up and which ones are cooling down. This deep local knowledge allows us to move with a level of confidence that out-of-state institutions simply can’t match. Whether you need fix and flip loans for a quick renovation or Airbnb loans to capitalize on the Valley’s tourism surge, we have the specialized tools to make it happen. We don’t just quote Phoenix hard money interest rates 2026; we deliver the leverage you need to win.
Why Level 4 Funding Beats the Competition
Urgency is our baseline. While other lenders are still checking your credit score, we’re already reviewing your ARV. We don’t have bureaucratic committees. We don’t have endless layers of management. You get direct access to decision-makers who understand the pressure of a closing deadline. We offer a shortcut to success by eliminating the friction that kills deals. Our process is designed for speed. Our mindset is designed for growth. We prioritize your ability to execute over rigid, outdated banking criteria. No red tape. No delays. No excuses. Just capital when you need it most.
Ready to Dominate the Phoenix Market?
Stop being a spectator. The Phoenix market doesn’t wait for bank approvals. It rewards the proactive. It rewards the bold. If you’re ready to stop losing deals to cash buyers, it’s time to change your funding strategy. The shortcut to your next $100k flip starts with a partner who moves as fast as you do. You’ve seen how Phoenix hard money interest rates 2026 are just one part of the profit equation. Now, get the leverage you need to solve the rest. Don’t let another high-spread property slip through your fingers because of a slow lender. Get your deal funded fast with Level 4 Funding and take control of your investment future today. Results start now.
Take Control of Your 2026 Phoenix Investment Strategy
The 2026 market doesn’t wait for bank committees. You’ve learned that Phoenix hard money interest rates 2026 are just one variable in a high-stakes profit equation. Success isn’t about finding the lowest decimal point. It’s about securing the asset before the competition even wakes up. Speed is your currency. Leverage is your weapon. You now have the roadmap to present deals that lenders can’t refuse. Focus on the ARV. Build a solid rehab budget. Let the property do the talking. Results matter more than formalities.
Level 4 Funding is your high-speed shortcut to capital. We provide asset-based lending that focuses on property value; not just your paperwork. We offer fast approvals across Phoenix, Scottsdale, and Tucson. Our expertise in Fix and Flip and Construction loans means we understand the street-level reality of your project. Stop letting bureaucratic red tape kill your ROI. It’s time to close deals in days, not months. The shortcut to your next six-figure profit starts with a single move. Don’t let hesitation cost you the deal.
Secure Your Phoenix Funding Now. Your next successful flip is waiting. Let’s get to work.
Frequently Asked Questions
What is the average hard money interest rate in Phoenix for 2026?
Phoenix hard money interest rates 2026 are driven by the specific risk of the property and your experience as an investor. You won’t find a single “average” because every deal is unique. Rates in the private sector are higher than bank loans because you’re paying for speed and the elimination of red tape. Every deal stands on its own merit. We focus on the asset’s value to determine the structure. Stop looking for a generic number. Find a rate that makes your flip profitable.
Do hard money lenders in Arizona require a minimum credit score?
We are an asset-based lender. This means we prioritize the property’s value over your FICO score. Traditional banks obsess over your past mistakes. We look at your future profit. While your financial history provides context, it isn’t the deal-breaker. No rigid credit hurdles. No bureaucratic disqualifications. If the deal is strong, we find a way to fund it. The property talks louder than the paperwork. Results matter more than your credit history.
How many points do hard money lenders typically charge in Phoenix?
Points are the upfront cost of doing business in the Valley. Most lenders in the Phoenix market charge between one and three points. This varies based on the loan’s complexity and your track record as an investor. Don’t just focus on the interest rate. Points are a critical part of your total cost of capital. We keep the process transparent. No hidden fees. No surprises at the closing table. You get direct access to capital without the games.
Can I use a hard money loan for a rental property or Airbnb in Scottsdale?
Absolutely. We offer specialized Airbnb loans for investors targeting Scottsdale and the surrounding Valley. Short-term rentals are high-growth assets in 2026. Traditional lenders don’t understand the nuances of the STR market. We do. We fund acquisitions and renovations for properties destined for the rental market. No long waits for bank appraisals. Just fast capital to help you secure a prime Scottsdale location before the competition. Your next rental income stream starts with fast funding.
How fast can I get a hard money loan approved in Phoenix?
Speed is our primary advantage. We can often approve a deal in 24 to 48 hours once we have the property details. Closing typically happens in 7 to 10 days. Compare that to a bank’s 45-day slog. No endless committees. No red tape. We move at the speed of the Phoenix market. If you have a distressed property under contract, you need a lender who can strike today. Don’t let a slow approval kill your profit.
What is the difference between LTV and ARV in hard money lending?
LTV is Loan-to-Value, based on the current purchase price. ARV is After-Repair Value, which estimates what the property is worth after your renovations. Most Phoenix hard money interest rates 2026 are influenced by these two numbers. We focus heavily on ARV because it reflects the true potential of your flip. A strong ARV backed by solid comps gives us the confidence to provide maximum leverage for your project. Don’t guess. Use real data to win.
Are there prepayment penalties on Phoenix hard money loans?
Every lender is different, but we prioritize your flexibility. Many of our loan structures lack the punitive prepayment penalties found in traditional banking. We want you to exit the deal quickly. Why should you be punished for being efficient? If you finish your flip in four months instead of six, you should be able to pay off the loan and move to the next deal. Results matter. Efficiency should be rewarded, not taxed by a bank.
What happens if I need an extension on my fix and flip loan?
Construction delays happen. We understand the Phoenix market’s challenges. If you need more time, we discuss extension options before your term expires. We aren’t a faceless institution looking to foreclose at the first sign of trouble. We are your ally. Communication is key. We work with serious investors to ensure their projects reach the finish line. No surprises. Just solutions for active flippers. We value your success as much as you do.
About the author
Matt has a bachelor's degree in political science from Northern Arizona University and works at Level 4 Funding, a private lending company that offers hard money and rental home loans to real estate investors in 35 states.
With Matt's leadership, the firm has financed almost $300 million in loans for investment properties. He often helps real estate investors with rental property purchases, foreclosures, refinancing, and fix-and-flip projects. Matt has extensive experience in fix-and-flip, buy-and-hold, rental properties, and real estate sales. He has lived in Arizona for 43 years and is married with three children. Matt is licensed as a mortgage broker and loan originator in Arizona, with NMLS 2062278 and NMLS 1118493.
Equal Housing Opportunity. This is not a Good Faith Estimate, and it is not a Guarantee to lend; it should not be considered as such. Costs, rates, estimates, and terms can only be determined after a full application is completed. To the extent this message includes any tax or legal advice, this message is not intended or written by the sender to be used, and cannot be used, for legal or tax purposes or advice. This is an advertisement. Copyright © 2026. All rights reserved.