
Commercial Bridge Loans vs. Hard Money Loans: Which Is Right for Your Next Commercial Deal?
November 13, 2026
Best Fix and Flip Lenders for Real Estate Investors: What to Look for and How to Compare
November 14, 2026
A slow sale doesn’t automatically sink a Phoenix flip, but waiting without a plan can squeeze your exit. A traditional listing may spend 30 to 60 days on the market before going under contract, then take another 30 to 45 days to close. If you’re weighing what to do if your flip in Phoenix doesn’t sell, start by comparing the time you can afford to hold the property with the net proceeds each sale option could leave you.
It’s frustrating to carry mortgage payments and other expenses while your property sits, especially if the market shifts or a seasonal slowdown affects buyer activity. You don’t have to make a rushed decision, but you do need a clear next move. This article compares staying on the market, selling to a cash buyer, considering an iBuyer, and exploring creative terms. You’ll see how timelines, mortgage payoff, and the likely trade-off between speed and proceeds can shape your choice, so you can act with a plan instead of guessing.
Key Takeaways
- Compare the net proceeds and timing of a price adjustment, rental, or faster-sale route before choosing your exit.
- Use buyer feedback and comparable Phoenix listings to decide whether a price reduction could help attract offers.
- Weigh realistic rental income against mortgage payments, upkeep, vacancy, and the work of managing a tenant.
- Map the steps and expenses involved in converting a finished flip into a rental before changing your plan.
- Explore financing options that fit your next investment, including a Fix and Flip Loan or Cash Out Refinance.
Situations where a fast sale may be preferable
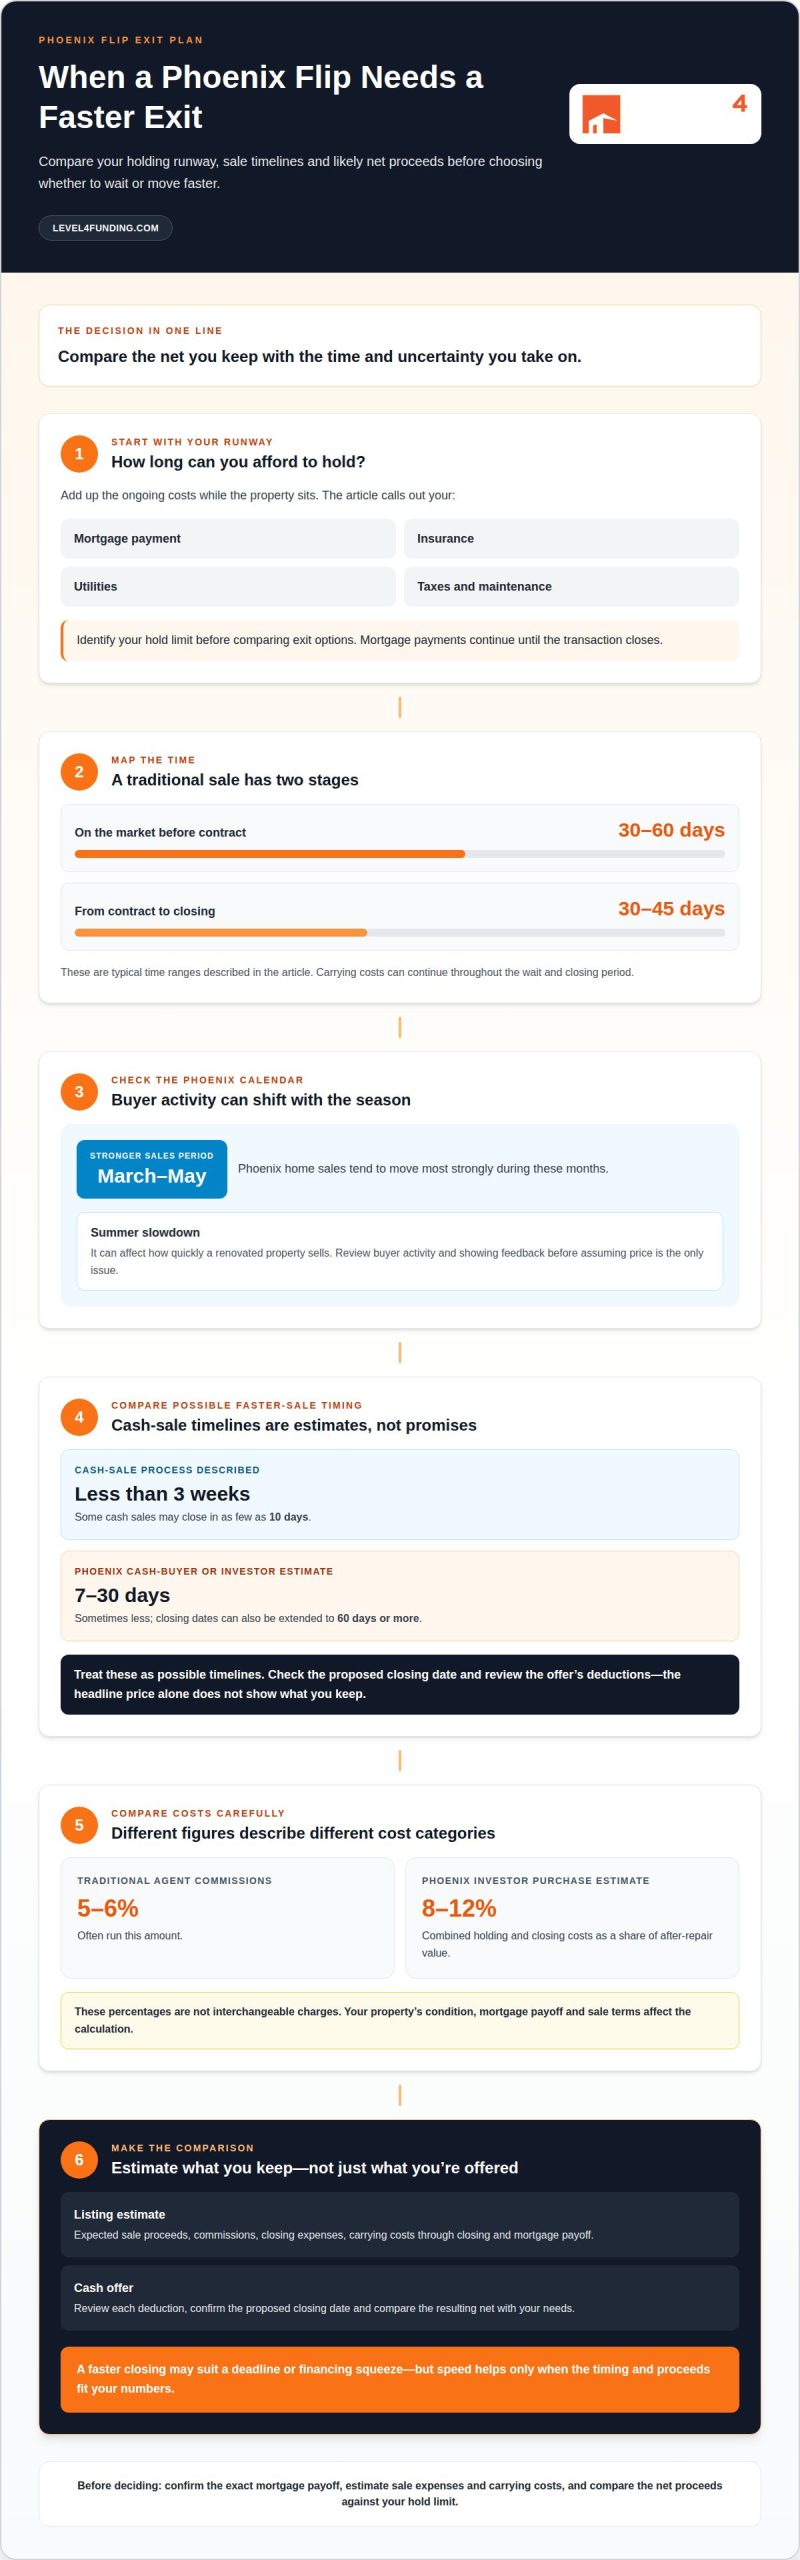
A fast sale may make sense when carrying a Phoenix flip is shrinking your expected profit. A traditional listing typically spends 30 to 60 days on the market before going under contract. Closing then typically adds another 30 to 45 days. Add your monthly mortgage payment, insurance, utilities, taxes, and maintenance to see what waiting could cost. The comparison is not just asking price versus cash offer. Estimate the proceeds after expenses, then weigh them against the time and uncertainty of each route. If you’re asking, “What if my flip in Phoenix doesn’t sell?” start by identifying how long you can afford to hold it.
Seasonality can affect your timeline, too. Phoenix home sales tend to move most strongly from March through May, while summer slowdowns can affect how quickly a renovated property sells. If your listing falls outside that stronger period, review buyer activity and showing feedback before assuming price is the only problem. A price cut may help, but it doesn’t remove the time needed to find a buyer and close. A cash-sale process may take less than three weeks from offer to closing; some cash sales can close in as few as 10 days. Treat those as possible timelines, not proof that an offer’s net value works for you.
If you face a deadline or a financing squeeze, speed may matter more than holding out for a higher price. Get the exact mortgage payoff, then subtract expected sale expenses and carrying costs through closing. Compare the estimated net with the cash you need to clear the debt and move on. A sale price that looks acceptable may leave too little after payoff. Check how the proposed closing date fits your loan obligations. An offer is not money in hand, and mortgage payments continue until the transaction closes.
Speed can bring a proceeds trade-off. Traditional real estate agent commissions often run 5 to 6 percent. A Phoenix investor purchase estimate places combined holding and closing costs at 8-12% of after-repair value. Those figures represent different cost categories, so don’t compare them as interchangeable charges. Your property’s condition, payoff, and sale terms change the calculation.
Before choosing a faster route, compare a likely listing outcome with a documented cash offer. Include expected sale proceeds, commissions, closing expenses, carrying costs, and mortgage payoff in the listing estimate. For the cash offer, review each deduction and the proposed closing date. A Phoenix cash-buyer or investor sale is estimated to take 7-30 days, sometimes less, but closing dates can also be extended to 60 days or more. Ask yourself, “What if my flip in Phoenix doesn’t sell before I need to free up capital?” That deadline can help clarify whether speed is worth the trade-off.
- Consider a fast sale when carrying costs or a deadline outweigh the likely benefit of waiting.
- Keep the listing strategy when buyer feedback supports the price and you can manage the timeline.
- Compare net proceeds after payoff and sale expenses, not just the headline offer.
A faster closing helps only when its timing and proceeds fit your numbers. Compare the payoff, sale deductions, and proposed closing date before deciding.
How should I price-reduce a Phoenix flip to attract buyers?
Base a price change on buyer feedback and competing homes, not frustration. If you’re asking, “What if my flip in Phoenix doesn’t sell?” start by finding out what buyers are responding to. Separate comments about price from objections about condition, layout, or location. Ask your listing agent to explain how your property compares with nearby homes of similar size and finish. A reduction can help when the asking price is out of line, but it won’t resolve a feature buyers consistently find unattractive.
Use active listings as reference points, not proof of market value. Compare your home with Phoenix properties only when location, layout, and condition make the comparison meaningful. Asking prices show what sellers hope to receive, not what buyers ultimately pay. Find the closest available matches and note the differences before revising your price.
Set your minimum net proceeds before changing the asking price. Start with the mortgage payoff, then subtract expected selling expenses and carrying costs through closing. Compare the result with the amount you need to recover or reinvest. This prevents a lower list price from seeming successful while leaving too little after expenses. If the revised price would fall below your acceptable net, weigh the cost of holding the property against changing your exit strategy.
Make one purposeful adjustment rather than several small cuts without a clear reason. Tie the new asking price to buyer comments, comparable listings, and your target net proceeds. Then track whether inquiries, showings, and offers change. If interest rises but buyers keep raising the same repair concern, consider whether addressing it could strengthen the listing. If activity remains flat, revisit the comparisons and presentation. Don’t assume every quiet week calls for another reduction.
- Compare like with like: Prioritize nearby homes with similar layout, condition, and renovation quality.
- Know your floor: Account for the payoff and selling expenses before setting a new price.
- Measure the response: Use showings and buyer feedback to judge whether the change is working.
A high offer still deserves scrutiny. Review the written terms as well as the price. Neither sets a rule for your property, so compare the offer with its condition, likely proceeds, and proposed terms.
Before deciding how to sell, compare a listing estimate with a cash offer that shows its calculation. These are two distinct benchmarks, not just competing headline prices. If you’re still asking, “What if my flip in Phoenix doesn’t sell?” use the figures to decide whether a price adjustment supports your plan or merely delays another decision. Record why you’re changing course, the net you expect, and what result would prompt a new strategy.
Should I rent out an unsold flipped house in Phoenix, and what are typical rents?
Renting can make sense when your Phoenix flip is move-in ready, expected rent supports the ownership costs, and you can hold the property. It turns a one-time sale into an ongoing investment. The key question isn’t simply whether someone might rent the home. It’s whether realistic rent in that neighborhood covers the mortgage, taxes, insurance, maintenance, and periods without a tenant.
There’s no single typical rent that fits every Phoenix flip. Estimate rent from comparable nearby rentals, not a citywide average. Match the number of bedrooms and bathrooms, square footage, condition, parking, outdoor space, and location. A renovated three-bedroom home near transit may appeal to a different renter pool than a similar home farther from major employment areas. Keep comparisons local and specific to the property.
Build your estimate with a simple process:
- Identify rental listings in the same Phoenix neighborhood or nearby area.
- Compare homes with similar bedroom counts, bathrooms, size, and amenities.
- Separate renovated properties from rentals with older finishes or deferred maintenance.
- Use the closest matches to set a realistic rent range, then test the lower end against your monthly expenses.
For example, if your flip has two bedrooms and one bathroom, don’t use a four-bedroom home as your main comparison. A pool, garage, yard, or upgraded kitchen can affect how renters view otherwise similar homes, as can commute patterns and nearby services. Note the differences between your property and each comparison. That makes your rent estimate more useful than copying the highest asking rent nearby.
Next, calculate the rental’s monthly break-even point. Add the mortgage payment, property taxes, insurance, routine upkeep, and any expected management expense. Compare the total with a conservative rent estimate, not the most optimistic listing. Leave room for turnover, repairs, and vacancy. If the numbers work only when every month is occupied and nothing needs fixing, renting may strain your cash flow rather than ease it.
Consider the work involved, too. A tenant may report a maintenance issue while you’re managing another project. You’ll need a plan for screening applicants, collecting rent, handling repairs, and keeping records. Decide whether to manage the home yourself or pay for help, then include that cost in your calculation. A polished renovation can attract interest, but it doesn’t remove a landlord’s responsibilities.
Renting is more compelling when the property suits local renter demand and projected income leaves room for ownership expenses. Selling may fit better when you need to recover capital for another project or the rent estimate falls short of monthly obligations. Compare projected rental cash flow with net sale proceeds and your investment timeline. That side-by-side comparison is more useful than deciding based only on renovation costs.
- Use nearby rental comparisons that match the home’s size, layout, condition, and features.
- Test conservative income against the mortgage and recurring ownership expenses.
- Account for management duties before deciding whether rental income fits your investment plan.
What are the costs and steps to convert a Phoenix flip into a rental property?
Turning a Phoenix flip into a rental shifts your focus from sale preparation to long-term ownership. Start by reviewing the property’s condition, your loan terms, and realistic expected rent. The conversion budget depends on what the home still needs, how you’ll manage it, and whether it can attract tenants as-is. Even a finished renovation may need safety repairs, durable materials, or rental-ready appliances.
Build a clear cost picture before advertising the home. Separate one-time expenses from recurring costs to understand the rental’s cash flow. One-time costs may include repairs, cleaning, replacement appliances, locks, and changes needed for tenant use. Ongoing costs include mortgage payments, property taxes, insurance, utilities during vacancy, routine maintenance, and property management if you use it. Costs depend on the home and your ownership plan, so use actual quotes and account records rather than a generic estimate.
Use this sequence to organize the conversion:
- Review financing: Read the current loan documents for terms affecting occupancy, leasing, or a change in property use. Include the payoff and monthly payment in your holding calculation.
- Inspect the finished work: Walk through each room and list incomplete repairs, damaged finishes, appliance gaps, and maintenance concerns.
- Price the rental: Compare nearby Phoenix rentals with similar layouts, condition, and features. Test the expected rent against recurring expenses.
- Complete required work: Schedule repairs and any permitting steps before a tenant moves in.
- Prepare operations: Decide who will handle tenant communication, rent collection, repairs, and records.
Permits matter when a renovation changes the property’s systems or structure. In Phoenix, projects involving structural changes, electrical updates, or major plumbing work must follow the proper city or county permitting process. Keep permit records and contractor documentation with the property file. This paperwork helps you track completed work and explain the home’s condition during future maintenance or a later sale.
Protect the budget from unfinished surprises. Phoenix flippers are advised to reserve a contingency fund of around 10 to 15 percent of the total renovation budget for unexpected repairs. If the flip is already complete, review invoices and inspection findings to identify remaining risks. A roof concern, plumbing issue, or electrical defect can turn into a landlord expense after occupancy. Resolve known problems before leasing rather than letting a tenant discover them first.
Then compare the rental plan with selling. Include the mortgage, taxes, insurance, repairs, vacancy, and management in your rental calculation. Compare that with estimated net sale proceeds and the capital you would recover. For example, a renovated Phoenix home that rents well but needs ongoing repairs may produce less usable cash than expected. A property with sound systems and a layout suited to local renters may be a better fit for a longer hold.
For investors weighing financing around a rental-focused property strategy, explore commercial property loan options.
Level 4 Funding: Fix and Flip Loans
Level 4 Funding offers Fix and Flip Loans for investors financing a property renovation and resale. If a Phoenix flip isn’t selling, reviewing the project’s financing can help clarify your next move, especially when ongoing expenses affect your plan. A loan isn’t a substitute for comparing sale proceeds, rental income, and carrying costs. It can, however, fit the financing needs of a future flip or construction project. For a property you plan to hold as an investment, Commercial Property Loans or Cash Out Refinance may also be relevant options. Match the financing conversation to the property, its intended use, and your investment strategy. Have questions about financing your next real estate project? Contact Level 4 Funding.
Choose the Next Move That Protects Your Investment
If you’re asking, “What if my flip in Phoenix doesn’t sell?” make your next decision based on the numbers, not the pressure of an empty showing calendar. Set a clear point at which you’ll change course. Decide what outcome you need, how long you can carry the property, and whether keeping it supports your broader investment plan.
The next project deserves the same discipline. Level 4 Funding offers Fix and Flip Loans and Construction Loans for renovation and building projects, plus Commercial Property Loans for investment properties. These options address financing for real estate projects, not a guarantee that an unsold home will sell or rent. Match the financing conversation to the project you’re planning and the role the property will play.
Ready to discuss financing for your next real estate move? Contact Level 4 Funding to talk through the options. Make a deliberate decision, protect your runway, and move forward with a plan.
Frequently Asked Questions
Questions about your specific situation?
Start with three figures: your current mortgage payoff, monthly carrying costs, and the net proceeds you need from the property. Compare them with a realistic sale estimate and a rental cash-flow projection. For a Phoenix flip, also consider buyer feedback and whether the home competes with similar nearby listings. This gives you a practical framework: adjust the listing, change your exit strategy, or hold only if the numbers support it.
What are the options if a house flip in Phoenix does not sell?
You can revise the asking price, sell to an investor, rent the home, or keep it listed while reassessing its market position. Compare each option by its effect on cash after mortgage payoff, the work involved, and how long you can carry the property. A rental plan may preserve ownership but tie up capital, while an investor sale may offer a different closing structure. Choose based on your financial priority, not frustration.
What are the average days on market for homes in Phoenix, Arizona?
A traditional Phoenix listing typically spends 30 to 60 days on the market before going under contract. Days on market measures the listing period, not the full time until your sale funds. Compare your property’s listing period with similar homes nearby, including their condition and asking prices. A home that has been listed longer than its closest competitors may need a fresh pricing or marketing review, while one matching local patterns may simply need more time.
Can I refinance an unsold flip in Phoenix, and what loan options are available?
Yes, refinancing may be an option to evaluate if you plan to retain the property rather than sell immediately. Level 4 Funding offers Cash Out Refinance, alongside financing options for real estate investment projects. Before choosing a refinance, clarify whether the property will be held as a rental or used in another investment plan. Compare the existing payoff and loan terms with the proposed structure, then assess whether the resulting payment works with your expected property income.
When should I consider selling an unsold flip to an investor or at auction?
Consider selling to an investor when a defined closing timeline matters more than pursuing the highest possible listing price. Before signing, compare the offer’s net proceeds with your payoff and sale expenses. Have the transaction close through a title company, and find out whether the buyer plans to assign the purchase contract. An auction is another option to assess if you need a structured sale process, but weigh its terms and likely proceeds against your deadline and financial floor.
About the author
Matt has a bachelor's degree in political science from Northern Arizona University and works at Level 4 Funding, a private lending company that offers hard money and rental home loans to real estate investors in 35 states.
With Matt's leadership, the firm has financed almost $300 million in loans for investment properties. He often helps real estate investors with rental property purchases, foreclosures, refinancing, and fix-and-flip projects. Matt has extensive experience in fix-and-flip, buy-and-hold, rental properties, and real estate sales. He has lived in Arizona for 43 years and is married with three children. Matt is licensed as a mortgage broker and loan originator in Arizona, with NMLS 2062278 and NMLS 1118493.
Equal Housing Opportunity. This is not a Good Faith Estimate, and it is not a Guarantee to lend; it should not be considered as such. Costs, rates, estimates, and terms can only be determined after a full application is completed. To the extent this message includes any tax or legal advice, this message is not intended or written by the sender to be used, and cannot be used, for legal or tax purposes or advice. This is an advertisement. Copyright © 2026. All rights reserved.