
How to Get Funding for a Quick Close Real Estate Deal in Phoenix
October 26, 2026
What Is a Capital Fund in Real Estate? How Private Capital Pools Power Investment Deals
Wondering what is capital fund real estate and how private pools of investor capital actually power deals? This article cuts through structure and jargon to show how real estate funds, syndications, and short-term private lenders fit into the capital stack, including where fast private lenders such as Level 4 Funding slot into time-sensitive transactions. You will get practical examples, compact deal math, and the key risks, fees, and timelines sponsors and investors must evaluate before committing capital.
1. What a real estate capital fund is and common fund types
Direct answer: if you are asking what is capital fund real estate, it is a pooled vehicle that aggregates investment capital to buy, develop, or lend against property. Structure matters because the legal form determines liquidity, fee mechanics, capital calls, and how fast managers can deploy money into deals.
Key mechanics: most real estate funds use a GP LP structure where the general partner manages assets and investors are limited partners. Expect a management fee to cover operations and a carried interest or promote that pays the GP on outperformance. Capital calls are common in closed end funds; evergreen funds typically accept subscriptions instead.
Common fund types and what they cost you
- Closed end fund: Blind pool raised for a fixed term, commonly 7 to 12 years. Good for concentrated value add or opportunistic strategies. Tradeoff: higher potential returns but long lockups and slower liquidity.
- Open ended or evergreen fund: Ongoing subscriptions and redemptions, often used by asset managers targeting income or steady allocations. Tradeoff: liquidity management can force sales in stressed markets, which compresses returns.
- Deal by deal syndication: Investors choose single assets; alignment is clearer and investors control each commitment. Tradeoff: higher transaction costs and slower scaling for sponsors.
- Club deal / co investment: Small group of investors directly buy an asset with bespoke terms. Tradeoff: limited diversification unless group repeats the model across multiple deals.
Practical tradeoff: blind pool funds buy speed and execution certainty for managers but demand trust from investors because asset selection happens after capital is raised. Deal by deal structures give investors choice and transparency but slow down deployment and complicate fundraising for sponsors.
Concrete example: Large closed end funds run by institutional managers such as Blackstone or Brookfield raise blind pools to execute global opportunistic strategies and use leverage at scale. By contrast, platforms like Fundrise and RealtyMogul operate evergreen or interval vehicles that accept smaller investors and offer more frequent liquidity but typically target lower net returns and higher fee layering for the retail channel.
What to watch as a sponsor or investor: management fees alone are noise. Check GP coinvestment, waterfall hurdles, and how the fund intends to source deals. A manager with low fees but zero skin in the game will often take more risk with your capital; alignment matters more than a 0.5 percent fee swing.
Bottom line: pick the fund form to match your timeline and liquidity needs; do not confuse lower headline fees with better alignment or speed of execution.
2. How private capital pools fit into the capital stack
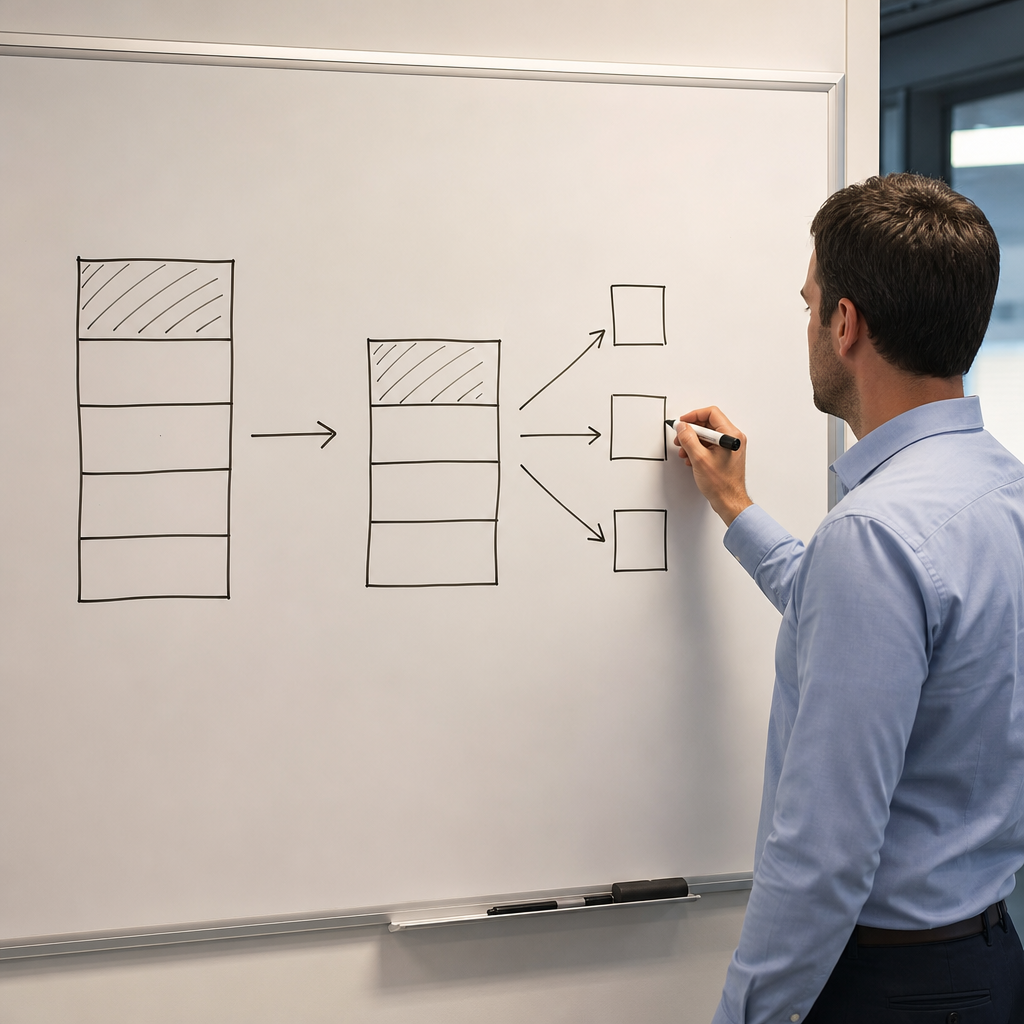
Private capital typically fills the nonbank tranches and the equity position that banks will not touch. In practice that means private credit funds and hard money lenders supply bridge and mezzanine debt while pooled equity from real estate funds, family offices, and syndications sits at the bottom of the stack accepting development and market risk.
Typical capital stack and who supplies each tranche
- Senior debt: Commercial banks, life companies, and agency lenders. Lowest cost but slowest and strictest on property stabilization and covenants.
- Mezzanine / private credit: Private credit funds and hard money lenders. Faster execution, higher interest, and more flexible underwriting for non stabilized assets.
- Preferred equity: Family offices and some specialist funds. Hybrid capital that sits above common equity, reduces lender exposure, and demands fixed preferred returns.
- Common equity: Real estate funds, private equity, syndication investors, and HNW individuals. Highest return target and greatest control over asset management.
Practical tradeoff to remember: speed costs money and control costs dilution. Private credit gets deals closed quickly but raises the effective cost of capital, which compresses sponsor upside or forces higher project returns. Conversely, bringing in equity partners lowers debt dependence but introduces governance, reporting, and longer time horizons.
Concrete example: A Phoenix fix and flip has purchase 300000, rehab 80000, ARV 450000. A fast private lender willing to underwrite to 70 percent LTV of ARV can provide up to 315000 in bridge financing, leaving the sponsor to supply 65000 of equity to cover cost gap and closing. That structure lets the sponsor close and rehab within weeks, then sell or refinance into permanent financing; banks would likely not approve that acquisition on a comparable timeline.
Real world use case: For a 30 unit value add multifamily, a sponsor may layer a senior construction loan from a regional bank for 50 percent of cost, a private bridge loan for 15 percent, and raise the remaining 35 percent from a pooled equity fund targeting value add returns. That mix shortens construction start times while preserving equity partner upside.
Meaningful judgment most sponsors miss: not all private capital behaves the same even if it sits in the same tranche. A private credit fund with institutional LPs will behave more like a bank on covenants and reporting than a small hard money shop, and equity from a blind pool fund will push for different exits than a local family office co investor. Treat provider type as a variable, not a label.
| Tranche | Typical providers and trade off |
|---|---|
| Senior debt | Banks, life companies – low cost, slow, requires stabilization |
| Private credit / hard money | Debt funds, hard money lenders – fast, higher cost, flexible covenants |
| Preferred equity | Family offices, specialty funds – reduces lender risk, higher fixed returns |
| Common equity | RE funds, syndications, HNW – highest return, longest illiquidity, most control |
Next consideration: When you are negotiating capital, quantify timing, required covenants, and exit flexibility up front. Those three dimensions determine whether a private pool of capital is a partner that unlocks a deal or a cost center that reduces ultimate returns.
3. How funds underwrite and execute deals
Underwriting is where strategy becomes executable math. Funds turn market views into line items: purchase assumptions, rehab schedules, financing costs, exit scenarios, and sensitivities that determine whether a deal fits the fund's risk-return profile.
Core underwriting checklist
- Market due diligence: recent comps, vacancy and rent trends, and comparable cap rates in the specific submarket.
- Acquisition math: purchase price relative to as-is comps, immediate upside, title or environmental flags that could change cost or timing.
- Renovation budget and schedule: line-item scope, contractor bids, contingency (usually 10 to 20 percent), and realistic draw timing.
- Exit assumptions: ARV or stabilized NOI, sales costs or refinance terms, and multiple exit scenarios (best, base, stressed).
- Capital structure and costs: senior debt pricing, holdbacks, interest reserve, mezzanine or preferred equity terms, and GP coinvestment levels.
- Sensitivity analysis: hold period, 5 to 15 percent ARV movement, and cost overruns to show where returns break down.
Practical point: underwriters assume friction — lender fees, holdbacks, longer sale timelines. In practice, deals win when sponsors shorten the timeline and control rehab execution, but that increases execution risk and compresses contingencies.
Deal execution mechanics
- Commitment to close: once the fund or lender signs terms, they issue a commitment letter with conditions precedent; speed here matters for competitive acquisitions.
- Funding and draws: acquisition disbursement, staged construction draws after inspection, and retained holdbacks until final completion. See our explainer on holdbacks for how lenders protect capital What Are Holdbacks in Construction Lending? Explained.
- Monitoring and reporting: weekly or biweekly construction reports, certified draws, and monthly investor reporting from funds (cash flows, NAV, variance versus pro forma).
- Exit and distribution: sale or refinance pays down senior debt, allocates carried interest per the waterfall, and distributes residual proceeds to LPs according to agreed splits.
Limitation to watch: faster funding sources like private hard money cut time-to-close but often charge higher financing costs and tighter covenants. Use them to secure the acquisition, not as a permanent capital plan unless the math supports it — pairing a Level 4 Funding style bridge with permanent equity or a refinance is a common, practical approach.
Concrete example: 6-month fix-and-flip underwriting
| Line item | Assumption / Value |
|---|---|
| Purchase price | $200,000 |
| Rehab budget | $60,000 |
| Projected ARV | $350,000 |
| Acquisition loan (hard money; principal) | $130,000 |
| Construction holdback (draws) | $45,000 |
| Equity required (sponsor/fund) | $85,000 |
| Interest, fees (6 months est.) | $18,000 |
| Sales costs (8% of ARV) | $28,000 |
| Net to equity on sale (illustrative) | $129,000 |
| Illustrative profit to equity | $44,000 (1.51x equity multiple) |
Concrete Example: a fund or sponsor uses a fast private loan to close and manages draws against contractor inspections. If rehab finishes on schedule and ARV holds, the equity stack earns the spread after financing costs and sales fees. If ARV falls 10 percent or rehab overruns, returns erode quickly — sensitivity matters more than the headline IRR.
Underwriting winners focus less on optimistic upside and more on controlling schedule and capital friction. Speed helps you win an acquisition; conservative holdbacks and clear draw mechanics protect investors' capital during execution.
4. Performance metrics and fee structures that matter to sponsors and investors
Fees convert headline returns into reality. Sponsors chase gross IRRs and multiples; investors should focus on net IRR, cash receipts, and how fees and waterfalls carve up profit over time.
Which metrics actually move decisions
Net IRR vs gross IRR. Gross IRR shows deal-level performance before manager fees and carry. Net IRR is what investors keep after management fees, carried interest, and expenses. For decision-making, net IRR is the one that matters — not the headline figure managers advertise.
Equity multiple and cash-on-cash. Equity multiple measures total money back vs money in. Cash-on-cash and distribution timing matter more for sponsors with ongoing capital needs: a high multiple delivered after five years is not the same as steady distributions over three years.
- Typical performance thresholds. Core funds target ~6–9% net IRR, value-add around ~12–20% net IRR, opportunistic higher but with much higher variance.
- Management fees. Commonly 1–2% of committed or invested capital; charged annually and they drag cash flows, especially on longer holds.
- Carried interest and hurdles. Typical waterfall: 8% preferred return, then 20% carry with a GP catch-up. The hurdle rate, catch-up mechanics, and whether carry is charged on gross or net profit change investor outcomes materially.
- GP commitment. Expect 1–5% co-investment from the sponsor on smaller funds; low or no GP skin in the game is a red flag for alignment.
Practical trade-off. Higher management fees can pay for better asset management and faster execution, but they also reduce funds available for reinvestment and lower net returns. Choose the lesser evil: a slightly higher management fee with strong operator skill beats a cheap fund that regularly misses budget and extends hold periods.
Fee mechanics sponsors and investors routinely misread
Fee stacking and disguised charges. Acquisition fees, financing placement fees, refinancing fees, and disposition fees often get paid to the GP on top of the annual management fee. These add up and are often paid out before carried interest calculations — read the PPM for fee waterfalls, not the one-page pitch deck.
Committed versus invested capital base. Management fees based on committed capital favor LPs on a quick deployment; fees based on invested capital favor LPs on slow markets but shift burden to GPs early. Know which method the fund uses and how it changes during the investment period.
Leverage changes the math, not the risk. More leverage inflates IRR and multiple on paper but raises execution and refinancing risk. Funds that target high leverage and high carry should justify the extra risk by showing robust sensitivity analyses — otherwise treat their projected returns skeptically.
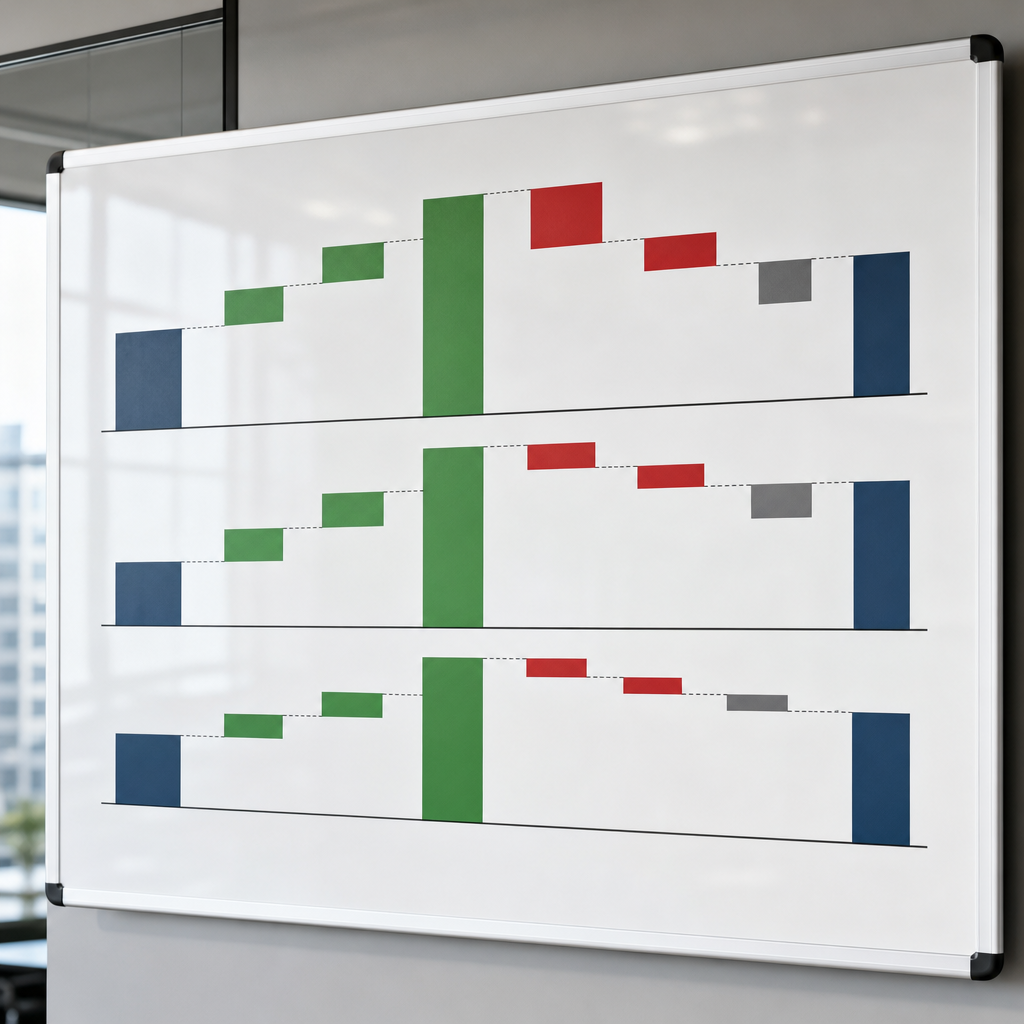
Concrete Example: Simplified numeric to show impact. A $1,000,000 equity stake that becomes $2,000,000 in three years (gross equity multiple 2.0x, gross IRR ≈26%) looks strong on paper. If the fund charges 2% annual management fees on committed capital and 20% carry above an 8% preferred return, the LPs end up with roughly $1.8M after fees — lowering net IRR to about 21–22 percent in this simplified scenario. The takeaway: fees and hurdle mechanics can shave several percentage points off headline IRR even on a successful deal.
Short-hold deals behave differently. For fix-and-flip sponsors, management fees and carried interest are less relevant than loan interest, transaction fees, and holdbacks. Use fast private lenders or short-term credit when speed matters; see our notes on construction holdbacks and fast private funding in the What Are Holdbacks in Construction Lending? Explained guide.
Important: never compare gross IRRs from different funds without normalizing for fee structures, leverage assumptions, and holding periods.
Where to dig next. Ask for a modeled investor cash flow showing pre-fee and post-fee waterfalls for multiple exit scenarios. Cross-check manager claims against audited results or verifiable deal sheets. For regulatory background on private funds, see the SEC guidance on private funds: SEC Private Funds.
Next consideration: When evaluating a fund, run your own sensitivity on hold period, leverage, and fee stacking. If the model falls apart with a modest delay or a small cap-rate move, the advertised returns are optimistic rather than reliable.
5. The role of speed and short term private lenders in powering deals
Speed wins deals more often than the cheapest bid. For sponsors competing in thin windows or buying assets that will not qualify for bank financing, short term private lenders provide decisive execution: fast underwriting, flexible collateral acceptance, and immediate liquidity that converts an LOI into a closed purchase.
How private short term capital actually moves faster
Process differences matter. Private lenders use in house credit teams, checklist underwriting focused on the asset and sponsor track record, and simplified draw schedules so decisions happen in hours or days rather than weeks.
- Pre-underwriting and soft approvals: lenders often issue conditional approvals from a phone call and a few documents.
- Asset centric focus: underwriting leans on comparable comps and rehab budgets rather than lender grade appraisal and debt service coverage ratios.
- Streamlined closing: title and funding can be coordinated to meet the contract close date rather than pushing it out for bank conditions.
Tradeoff to accept. Speed is not free. Expect higher interest, origination fees, shorter terms, heavier holdbacks, and stricter exit covenants. Use short term capital where timing creates value that exceeds these costs; do not treat it as a permanent capital solution for long hold strategies.
Concrete example: A Phoenix sponsor bids on a 3 bedroom in a competitive auction with a 7 day close. They secure a 24 hour conditional approval and funding commitment from Level 4 Funding at 65 percent LTV with a 12 month term and construction draws. The sponsor closes, completes a 60 day rehab, and sells in month three, using sale proceeds to repay the bridge loan and preserve margin.
Coordination with equity partners matters. When a sponsor pairs fast debt with fund equity, disclose the bridge economics up front. Equity investors will accept higher financing cost for a fast close if it preserves an attractive acquisition price, but unexpected rollovers or missed exits destroy trust and returns faster than a small rate differential.
- When to use short term private lending: competitive acquisitions, time sensitive rehab projects, bridge to permanent financing, or when banks will not underwrite a non stabilized asset quickly.
- When not to use it: long term holds without a defined refinance or sale path, deals that require long permit timelines, or when the sponsor lacks a reliable exit plan.
If you prioritize speed, build the exit plan before you sign the loan; a fast close without a credible exit turns a tactical advantage into a liability.
6. Common risks in capital funds and practical mitigations
Straight answer: capital funds fail most often from a mix of liquidity mismatch, too much leverage, and execution problems on rehabs — not from clever investment theses. Understanding which risk dominates your fund or deal lets you pick mitigations that actually change outcomes.
Primary risks funds face
- Liquidity risk: funds with long hold horizons or illiquid asset mixes can face forced sales when investors redeem or capital calls stall.
- Leverage risk: high LTV or aggressive use of mezzanine debt amplifies stress when rental cash flow or exit pricing weakens.
- Execution risk: value add projects fail when budgets, timelines, or contractor performance go off plan.
- Concentration risk: cluster bets by geography, asset type, or tenant profile can turn a local downturn into a fund-level loss.
- Valuation and pricing risk: reliance on stale appraisals or optimistic comps creates tail risk at disposition.
- Alignment and governance risk: weak GP coinvestment or nontransparent fee structures create perverse incentives and poor decision making.
Practical mitigations and real trade-offs
Diversification reduces idiosyncratic risk but raises operational complexity. Spreading capital across geographies or product types lowers the chance a single local shock forces fire sales, but it increases due diligence cost and the need for on-the-ground partners.
- Staged capital deployment and holdbacks: use construction draws and milestone holdbacks to ensure capital is only released as work is verified — see What Are Holdbacks in Construction Lending? Explained. Trade-off: slows disbursement and can reduce early IRR but prevents incomplete projects.
- Conservative leverage policy: cap overall LTV and limit mezzanine exposure. Trade-off: lower leverage reduces upside IRR but preserves optionality in downturns.
- Robust covenants and reporting: require monthly budget-to-actuals, lien waivers on draws, and vendor payment audits to catch drift early.
- GP coinvest and clawbacks: meaningful GP equity aligns decisions; clawbacks correct outsized sponsor payouts after losses.
- Liquidity buffers and subscription lines: keep reserve cash or a subscription credit line to bridge redemptions without fire sales, acknowledging lines add complexity and covenant risk.
- Third-party valuation and stress tests: independent appraisals and downside case modeling that stress rents, cap rates, and rehab overruns.
Judgment call: many funds over-index on deployment speed and underfund stabilization reserves. In practice, a 5 to 10 percent contingency held back for tenanting or unexpected repairs protects returns more reliably than chasing a few additional basis points of deployed capital.
Concrete example: A small value-add fund in the Sun Belt budgeted $1.8 million to renovate three small apartment buildings with 70 percent LTV financing. When a local supply chain delay doubled drywall lead times, the sponsor used staged draws plus a 7 percent contingency holdback to avoid paying contractors out-of-order and preserved enough cash to finish the projects without taking on expensive mezzanine debt. The fund accepted a slightly lower IRR because avoiding an emergency loan prevented a forced short-term sale at a depressed cap rate.
| Risk | Effective mitigation |
|---|---|
| Liquidity mismatch (redemptions vs illiquid assets) | Subscription lines, redemption gates, and reserve cash |
| Rehab execution overruns | Milestone holdbacks, approved contractor lists, and draw inspections |
| Concentration in one market | Geographic diversification and local market stress testing |
| Excessive leverage | Set conservative max LTV, limit tranche layering, enforce amortization |
Key takeaway: choose mitigations that address the fund's single biggest vulnerability — liquidity, leverage, or execution — rather than layering controls that feel comprehensive but leave the main risk untouched.
7. How sponsors and small investors should approach capital funds and private capital partners
Direct principle: match capital type to the deal timeline and the outcome you need. Private funds bring patient equity and governance overhead; private lenders bring speed and certainty. Choose one because it fits the transaction, not because it feels familiar.
Sponsor checklist before you solicit capital
- Select capital by constraint: if closing date is fixed or comps are moving, prioritize credit or bridge capital; if value add requires deep pockets and longer hold, seek fund equity.
- Assemble a concise package: one page deal summary, comps, rehab budget, pro forma and exit scenarios. Having a data room speeds any fund or lender decision.
- Clarify covenants and waterfall: know that funds will layer preferred returns and promotes. Negotiate limited covenants for short rehab deals; accept stricter covenants when taking long hold equity.
- Pre-commit contingency capital: line up a private lender to backstop closings when equity is still finalizing. See Hard Money Lender Meaning: Fast Funding for Phoenix Deals for how quick bridge capital lowers execution risk.
- Plan draws and holdbacks with partners: coordinate construction draws so equity is not stranded mid-rehab and lender holdbacks do not undercut completion.
- Set reporting expectations: funds want monthly updates and budgets; lenders require draws and inspections. Define responsibilities up front.
Investor checklist when evaluating a real estate fund
- Track record over promises: a clear history of similar deals matters more than marketing. Ask for realized returns on comparable assets, not model returns.
- GP coinvest and alignment: a meaningful GP commitment reduces the chance of value destruction from reckless leverage or churn.
- Fee economics and hurdle math: request a waterfall example showing net IRR at plausible exit prices. Small differences in promote materially change net returns.
- Liquidity and gating: understand capital call cadence, lockup periods, and how redemptions are handled in down markets. Review SEC private funds guidance for regulatory expectations.
- Stress scenarios: run downside occupancy, cap rate shifts, and cost overrun cases to see if the fund or sponsor can absorb shocks.
Tradeoff to accept: equity reduces immediate cash strain and shares upside but slows decision making and reduces control. Debt gives execution certainty and speed but increases default risk and reduces upside to sponsors. In practice, the most efficient deals use both in a coordinated stack rather than treating one as a fallback.
Concrete Example: A Phoenix sponsor has a $400k purchase with a $120k rehab. The sponsor secures a 65 percent LTV bridge from a private lender to close within 7 days, while a small local property fund commits equity for completion and reserves. The bridge covers acquisition and initial draws so the sponsor can start work immediately; the fund wires remaining equity at the first milestone, reducing timing risk and limiting carry cost.
If speed is the constraint, call the lender first and line up equity second. If capital size or risk appetite is the constraint, lock equity first and accept slower close.
Final consideration: prepare the information a partner needs to act quickly and know which tradeoff you accept – dilution, speed, or control. That choice determines whether you should call a private lender like Level 4 Funding or pursue fund equity first. Plan for the decision, then execute to that plan.