
Top Hard Money Lenders by Region: How to Find a Reputable Local Private Lender Anywhere
September 21, 2026
Waiting on a retail bank’s 45-day approval cycle doesn’t just stall your momentum; it kills your deal. In the Valley’s competitive market, mastering Phoenix BRRRR method financing isn’t about chasing the lowest possible interest rate. It’s about raw capital velocity. You already know the sting of watching an all-cash buyer snatch a prime distressed property in Mesa or Glendale while an underwriter nitpicks your personal tax returns, only to trap your working capital later behind rigid 12-month seasoning rules.
You shouldn’t have to sacrifice your entire pipeline to red tape. In this 2026 guide, you’ll discover how to secure fast, asset-based capital for every phase of your Phoenix BRRRR deals without traditional bank delays. We’ll map out how to lock down acquisitions in days, fund renovation draws on schedule, and liberate your equity through an agile cash-out refinance so you can roll straight into your next acquisition.
Key Takeaways
- Why rigid conventional underwriting kills distressed Valley deals, and how speed gives you the upper hand against institutional cash buyers.
- The operational blueprint of Phoenix BRRRR method financing, using hard money loans that underwrite after-repair value instead of your tax returns.
- A stage-by-stage playbook to lock down distressed acquisitions and draw renovation capital without bureaucratic delays.
- Proven strategies to bypass brutal 12-month seasoning traps and liberate your working capital using an agile cash-out refinance.
- The essential criteria for vetting hard money lenders beyond headline rates to protect your margins and guarantee closing certainty.
Why Conventional Lending Fails the Phoenix BRRRR Strategy in 2026
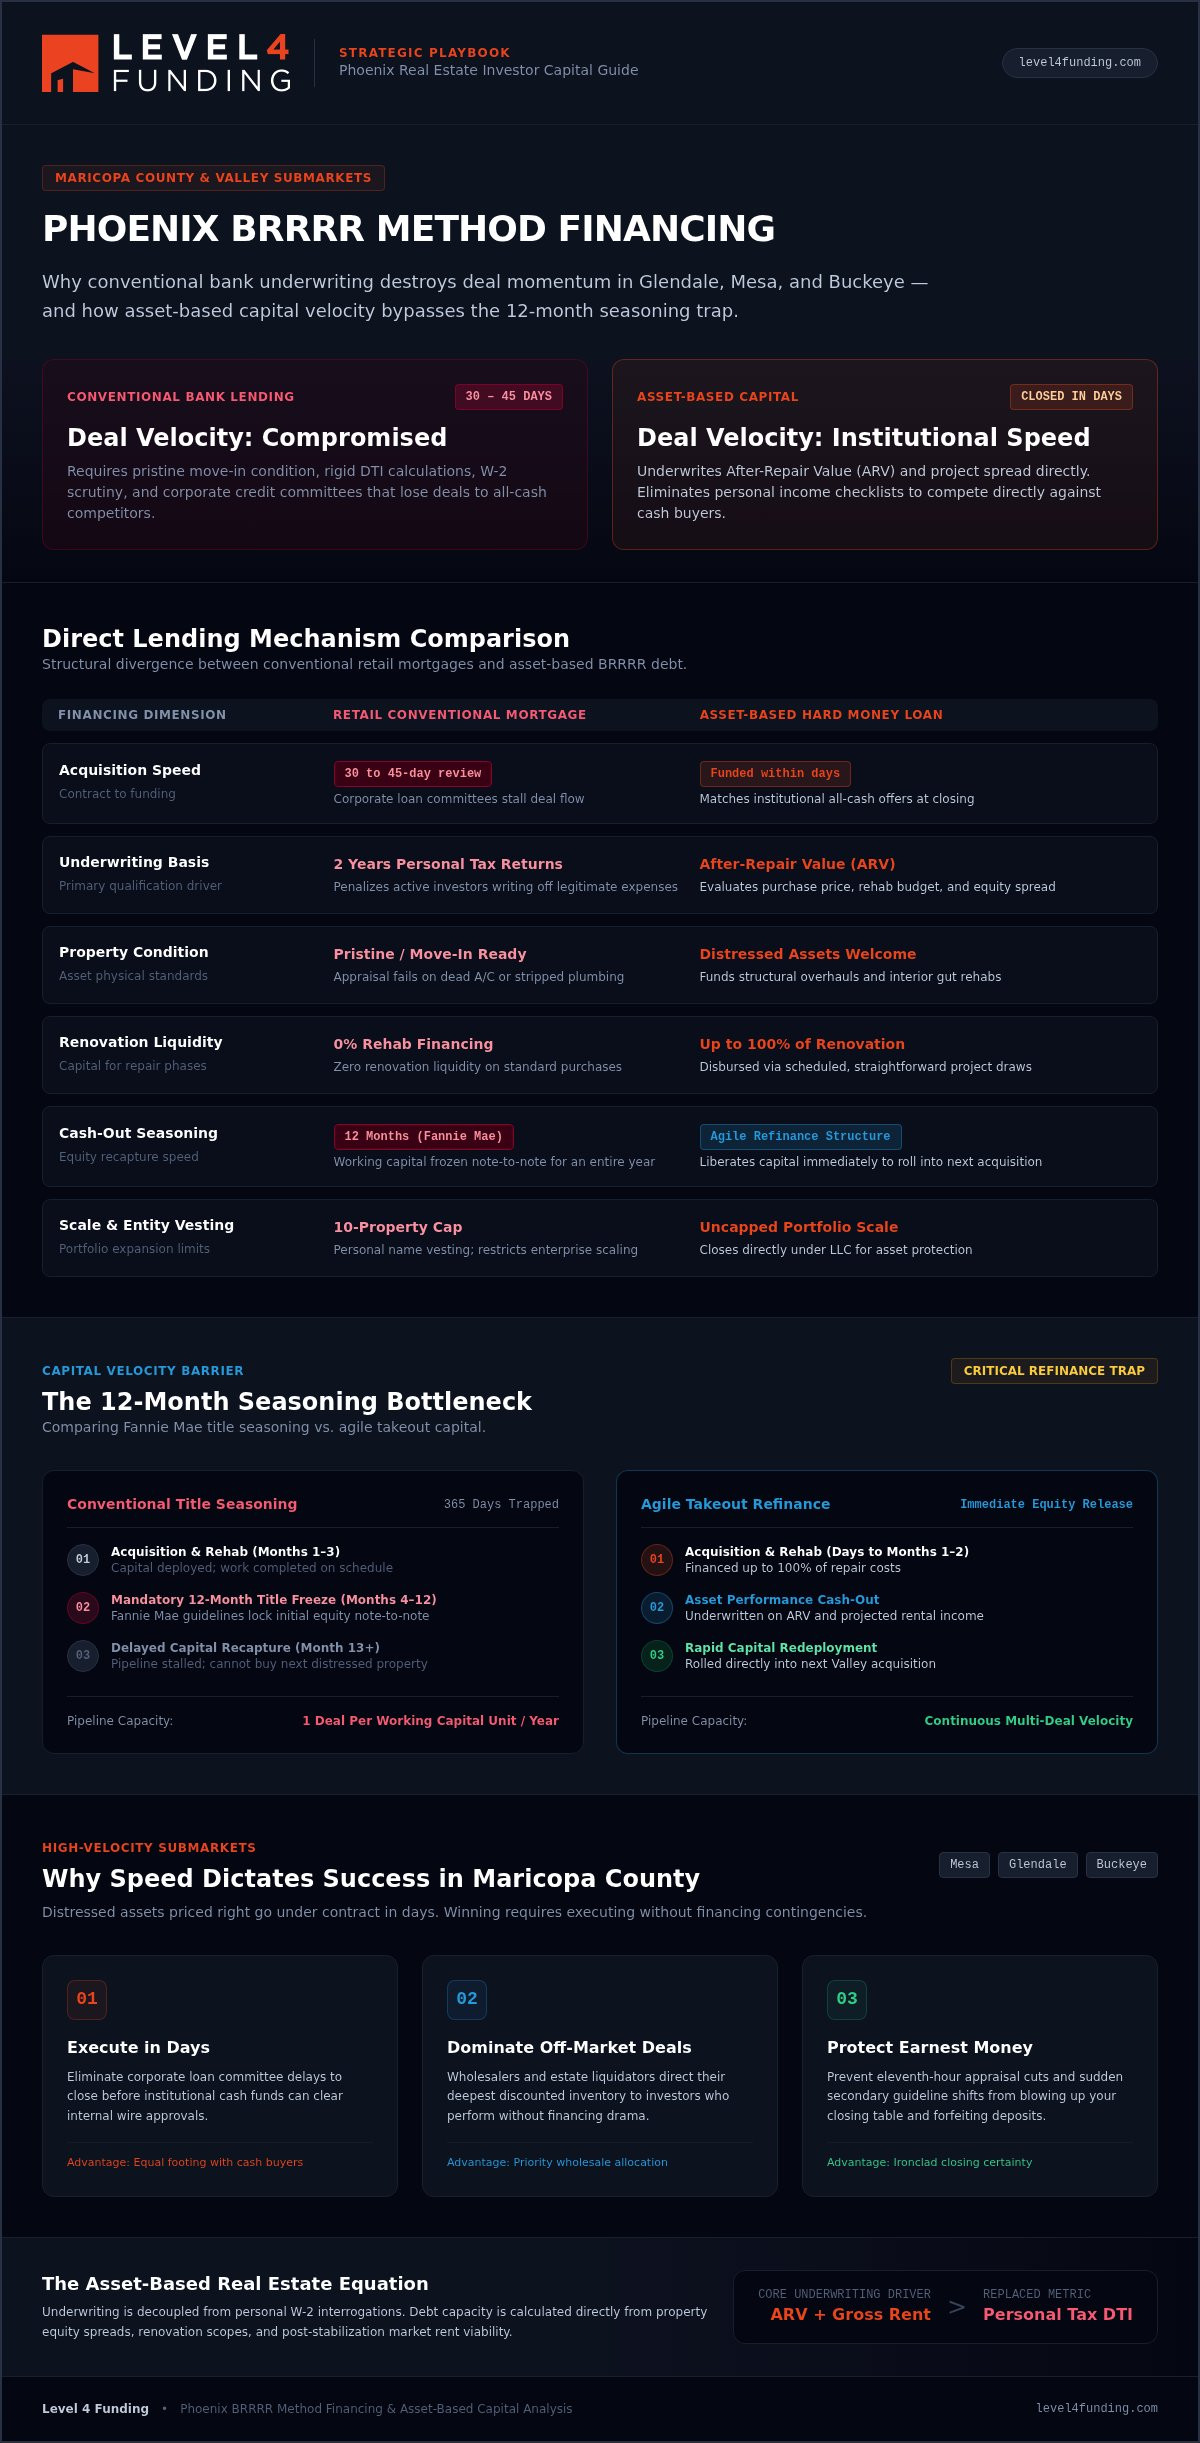
The Phoenix market doesn’t wait for bank credit committees. Distressed properties priced right across Maricopa County go under contract in days, not months. If you rely on traditional mortgage brokers, you lose before the race even starts. Retail banks don’t care about your deal’s equity spread or post-renovation cash flow. They care about red tape, personal debt-to-income ratios, and bureaucratic checklists. That mindset is completely incompatible with executing Phoenix BRRRR method financing at scale.
The Fatal Flaws of Bank Underwriting for Distressed Properties
Conventional guidelines demand pristine, move-in-ready homes. A dead air conditioning unit during a triple-digit Phoenix summer or a stripped copper plumbing line will immediately trigger a rejected appraisal. Traditional lenders refuse to touch high-upside assets needing structural overhauls or extensive interior gutting. Worse yet, their processors demand two years of personal tax returns, actively penalizing full-time investors who write off expenses to lower taxable income.
Savvy investors sidestep this bureaucratic wall by leveraging asset-based hard money loans to secure their projects. Direct private capital prioritizes the real estate itself: the purchase price, the renovation budget, and the after-repair value (ARV). No W-2 interrogations. No habitability delays. Just pure focus on the project’s bottom-line profitability.
The Speed Advantage in Phoenix Submarkets
In high-velocity submarkets like Glendale, Mesa, and Buckeye, distressed deals disappear almost instantly. Wholesalers and estate sellers demand absolute certainty, not a 45-day financing contingency that might crumble in secondary underwriting. Deploying agile Phoenix BRRRR method financing puts you on equal footing with institutional cash buyers.
- Execute in days: Eliminate corporate loan committees to close before institutional funds clear their wire approvals.
- Dominate off-market deal flow: Wholesalers funnel their deepest discounts to investors who consistently perform without financing drama.
- Protect your earnest money: Prevent eleventh-hour appraisal cuts and sudden guideline shifts from blowing up your closing table.
Financing Options for Phoenix BRRRR Deals Compared
Low interest rates mean nothing if you never secure the deed. Choosing the wrong debt structure leaves your working capital trapped and freezes your momentum. In competitive Arizona markets, structuring your Phoenix BRRRR method financing requires balancing capital speed, leverage thresholds, and underwriting flexibility.
Hard Money vs. Conventional Bank Loans for BRRRR Acquisition
Conventional investment mortgages offer attractive base interest rates, but they strangle active deal pipelines. They enforce rigid 10-property caps, demand endless documentation, and move at a crawl. More critically, official Fannie Mae cash-out refinance guidelines require 12 full months of title seasoning note-to-note before you can extract cash from an investment property. That one requirement locks up your cash reserves for an entire year.
In contrast, private financing underwrites the future profit of the project. Learn what is a hard money loan to bypass retail delays and secure distressed assets based on their after-repair value (ARV). You get speed, flexibility, and fast execution at the closing table.
Asset-Based Lending vs. Personal Credit Verification
Traditional lenders treat real estate operators like standard W-2 employees. They measure debt-to-income (DTI) ratios, scrutinize personal write-offs, and slash your borrowing capacity with every tax deduction your CPA takes. Asset-based lending flips that script completely.
Smart Valley investors rely on property performance. Explore how asset based real estate loans eliminate personal income verification hurdles by evaluating project equity and projected gross rents instead of personal tax returns. Here is how these financing tools stack up:
- Acquisition Velocity: Hard money closes within days, matching all-cash offers. Conventional mortgages crawl through a 30 to 45-day review.
- Rehab Funding: Asset-based lenders finance up to 100% of renovation budgets through straightforward draws. Banks offer zero rehab liquidity on standard purchases.
- Entity Protection: Private lenders let you close directly under your LLC. Retail banks force title into your personal name.
- Takeout Speed: Asset-based takeout options allow refinances in as little as 3 to 6 months. Conventional routes keep you trapped for 12 months.
If you need capital deployed rapidly to scale across Maricopa County, partnering with Level 4 Funding ensures your financing moves as fast as local deal flow demands.
The 5 Stages of Phoenix BRRRR Financing: Execution Playbook
Most investors treat BRRRR like five isolated transactions. That approach is a fatal mistake. True portfolio scaling requires viewing the strategy as a continuous capital engine where your takeout financing is already mapped before your acquisition bridge loan ever funds. Mastering Phoenix BRRRR method financing means executing each phase with zero friction.
Buy and Rehab: Securing Fast Acquisition and Construction Draws
Speed secures the contract, but disciplined draw management protects your margins. Partnering with specialists in fix and flip loans provides up to 100% of your renovation budget in escrowed disbursements. Never let construction stall waiting on capital. Establish milestone schedules with your private lender early, line up licensed Maricopa trades, and coordinate site inspections promptly so draw checks release within 48 hours.
Rent and Stabilize: Maximizing Valuations Across Maricopa County
Tenant placement is an underwriting event, not just a property management chore. In submarkets like Buckeye, Mesa, and Glendale, top-tier rents require smart upgrades: dual-pane low-E windows, updated HVAC systems that conquer 115-degree summers, and low-water desert xeriscaping. Strong property conditions lock in qualified tenants paying $1,800 to $2,300 monthly for single-family rentals.
A signed, executed lease supported by security deposits provides the verifiable income takeout lenders demand. In addition, Arizona’s elimination of the municipal residential rental sales tax streamlines your monthly bookkeeping, letting clean rental revenue flow directly to your operating bottom line.
Refinance and Repeat: Unlocking Cash to Scale Rapidly
The finish line of one deal is the down payment for your next. When your rehab finishes and your tenant takes occupancy, order your appraisal immediately. Historical tracking via the Phoenix-Mesa-Chandler house price index confirms long-term price stability across Valley submarkets, supporting forced equity valuations.
- Extract your initial capital: Tap an asset-based cash-out refinance at 75% to 80% loan-to-value to pull your original acquisition and rehab capital back out.
- Retire bridge debt: Pay off short-term construction financing cleanly without pre-payment drama.
- Re-deploy immediately: Funnel the liberated cash into your next distressed off-market contract to keep your money compounding.
Run this playbook methodically. When your capital moves continuously, your real estate wealth builds on autopilot.
Overcoming the Refinance Bottleneck: Seasoning and Takeout Financing
The cash-out refinance is where most Phoenix BRRRR investors hit a wall. You finish a high-end rehab, place a great tenant, and then discover your lender refuses to touch the property until you hold title for a full year. That delay strangles capital velocity. Overcoming this hurdle requires understanding how institutional takeout criteria differ from asset-based equity solutions in Phoenix BRRRR method financing.
Navigating Lender Seasoning Rules Without Freezing Capital
Traditional banks evaluate your refinance based on your original purchase price rather than current market value until strict holding periods expire. If you paid $300,000 for a distressed property and invested $70,000 to push its value to $450,000, conventional rules ignore that forced appreciation. You stay trapped.
By executing an asset-based hard money cash out refinance, you access liquidity based entirely on the newly appraised value. You do not have to wait 12 months. Non-QM and asset-based programs reduce seasoning windows to three to six months. When structuring your financing based on documented cost-basis, some asset lenders even waive seasoning requirements entirely. To defend that valuation against conservative appraisers:
- Compile an itemized scope of work: Hand the appraiser paid contractor invoices and permit sign-offs detailing structural and mechanical improvements.
- Provide active rental verification: Deliver signed lease agreements and bank deposits proving true market yields.
- Supply local neighborhood comps: Highlight recently closed, renovated properties within a one-mile radius across Phoenix or Scottsdale.
Streamlining Takeout Underwriting for Scaled Portfolios
Scaling past four properties breaks retail bank underwriting. Conventional loans force mortgages into personal names and penalize entity transfers. Asset-based takeout debt allows you to vest title directly inside an Arizona LLC, preserving asset protection and keeping business debt off your personal credit file.
Eliminate eleventh-hour closing surprises by mastering the hard money loan approval process. Line up takeout terms while your contractors are still completing exterior paint and landscaping punch lists. Do not wait for lease signing to start your refinance file.
Ready to pull your capital out and fund the next deal? Apply for cash-out refinance funding with Level 4 Funding to keep your investment momentum moving forward.
How to Choose Your Phoenix BRRRR Financing Partner
A cheap headline rate on a marketing flyer won’t save a deal when a lender goes dark three days before closing. Vetting your capital source is just as critical as analyzing your property comps. When you execute Phoenix BRRRR method financing, you need a lending ally that moves like an equity partner, not a bureaucratic roadblock.
Origination points, surprise junk fees, and sluggish draw inspections quickly destroy your profit margins if your lender hides behind fine print. You need absolute transparency from the initial term sheet to the final refinance payoff.
Key Questions to Ask Before Signing Loan Documents
Don’t sign a note until you get clear, written answers to these direct questions:
- Is leverage pegged to purchase cost or After-Repair Value? A lender capping leverage strictly at purchase cost forces you to bring heavy cash to closing. Demand capital calculated against true post-renovation equity.
- What are the draw schedule fees and inspection timelines? Find out how fast inspectors walk the job site and how quickly wire releases clear. Multi-day delays on construction draws stop contractor crews cold.
- Can you finance both the bridge loan and the takeout? Bouncing between separate acquisition lenders and takeout institutions creates execution friction. A unified capital pipeline keeps your timeline seamless.
- How quickly do you fund repeat deals? Once you establish a track record, your repeat acquisitions should fund with minimal back-and-forth paperwork.
Partnering with Level 4 Funding for High-Speed Execution
National lenders operate through disconnected call centers. They don’t know the difference between Central Scottsdale, Glendale, or Mesa. They rely on automated algorithms that panic over distressed properties and freeze your earnest money at the closing table.
You deserve better. As a trusted local hard money lender, Level 4 Funding deploys direct private capital across Phoenix, Scottsdale, Mesa, and Glendale. We focus on asset strength, projected ARV, and deal profitability rather than dissecting personal tax returns. From fast fix and flip loans that cover acquisition and rehab to agile cash out refinance debt that frees up your working capital, our platform gives active investors the leverage to scale.
Stop leaving your investment pipeline in the hands of corporate credit committees. Secure the asset-based capital you need to dominate the Phoenix market today.
Scale Your Valley Rental Portfolio with Unstoppable Capital
Capital velocity wins in Arizona real estate. Waiting around for 45-day bank approvals or letting your working cash get trapped behind rigid seasoning rules stops your business dead. Mastering Phoenix BRRRR method financing is about securing fast, decisive leverage so you can buy right, renovate with confidence, and recycle your liquidity without missing a beat.
When you rely on asset-based lending focused on true property ARV instead of endless tax returns, you eliminate friction. You close deals in days, outmaneuver institutional buyers, and protect your margins across Phoenix, Scottsdale, Mesa, Glendale, and Tempe.
Stop letting bureaucratic red tape dictate how fast your rental portfolio grows. Partner with local lenders who understand the street-level economics of the Valley market. Get pre-approved for your next Phoenix BRRRR deal with Level 4 Funding and lock down your next distressed acquisition with complete closing certainty.
Frequently Asked Questions
Can I use hard money financing for the entire BRRRR process in Phoenix?
Yes. You can leverage short-term hard money loans for acquisition and rehab, then transition directly into an asset-based cash-out refinance. Private lenders like Level 4 Funding provide bridge capital for the initial purchase and construction, followed by flexible takeout debt. This structure keeps your entire capital stack under one roof without the headache of managing separate retail banks across Phoenix and Scottsdale.
How do Phoenix lenders calculate After-Repair Value on a BRRRR property?
Lenders calculate ARV by evaluating recent closed sales of fully renovated comparable homes within a one-mile radius, combined with your detailed contractor scope of work. In submarkets like Mesa and Glendale, appraisers analyze square footage, structural layout, and essential upgrades like new HVAC units and desert landscaping. Your post-rehab equity potential dictates your borrowing limits, not your purchase discount.
What seasoning period is required before executing a cash-out refinance in Arizona?
While conventional agency guidelines demand a grueling 12-month seasoning window, asset-based lenders typically require only three to six months. If you structure the takeout based on your documented purchase price plus actual renovation costs, some private lenders waive seasoning completely. That flexibility lets you pull working capital back out without leaving your money idle for a year.
Do I need perfect personal credit to secure Phoenix BRRRR method financing?
No. Phoenix BRRRR method financing relies primarily on asset strength, property equity spread, and projected rental revenue rather than a pristine credit profile. Most asset-based private lenders look for a baseline score around 620 to 680. Underwriters focus heavily on the deal’s profitability and debt service coverage rather than personal tax write-offs or W-2 income verification.
Can I include renovation and construction costs directly in my acquisition loan?
Yes, fix and flip loans routinely fund up to 100% of your renovation budget alongside the initial purchase capital. The rehab funds sit in an escrow account. As your contractors hit verifiable construction milestones across Phoenix or Buckeye, the lender inspects the work and releases draw payments within 24 to 48 hours to keep your project moving forward without delay.
How fast can an asset-based private loan close on a Phoenix investment deal?
An asset-based private loan can fund in as little as 5 to 10 business days once title commitments and property valuations clear. Because private lenders eliminate corporate loan committees and personal income tax audits, approvals happen fast. This speed allows Valley investors to submit competitive, cash-equivalent offers that beat out retail buyers on off-market wholesale properties.
Why do Phoenix real estate investors choose private lending over conventional bank mortgages?
Speed, closing certainty, and property flexibility drive serious investors away from retail banks. Conventional lenders take 45 days, reject distressed homes with mechanical issues, and cap borrowers at 10 financed properties. Private hard money lenders underwrite the real estate, fund heavy construction scopes, and allow title vesting directly under Arizona LLCs for better asset protection.

About the author
Matt has a bachelor's degree in political science from Northern Arizona University and works at Level 4 Funding, a private lending company that offers hard money and rental home loans to real estate investors in 35 states.
With Matt's leadership, the firm has financed almost $300 million in loans for investment properties. He often helps real estate investors with rental property purchases, foreclosures, refinancing, and fix-and-flip projects. Matt has extensive experience in fix-and-flip, buy-and-hold, rental properties, and real estate sales. He has lived in Arizona for 43 years and is married with three children. Matt is licensed as a mortgage broker and loan originator in Arizona, with NMLS 2062278 and NMLS 1118493.
Equal Housing Opportunity. This is not a Good Faith Estimate, and it is not a Guarantee to lend; it should not be considered as such. Costs, rates, estimates, and terms can only be determined after a full application is completed. To the extent this message includes any tax or legal advice, this message is not intended or written by the sender to be used, and cannot be used, for legal or tax purposes or advice. This is an advertisement. Copyright © 2026. All rights reserved.